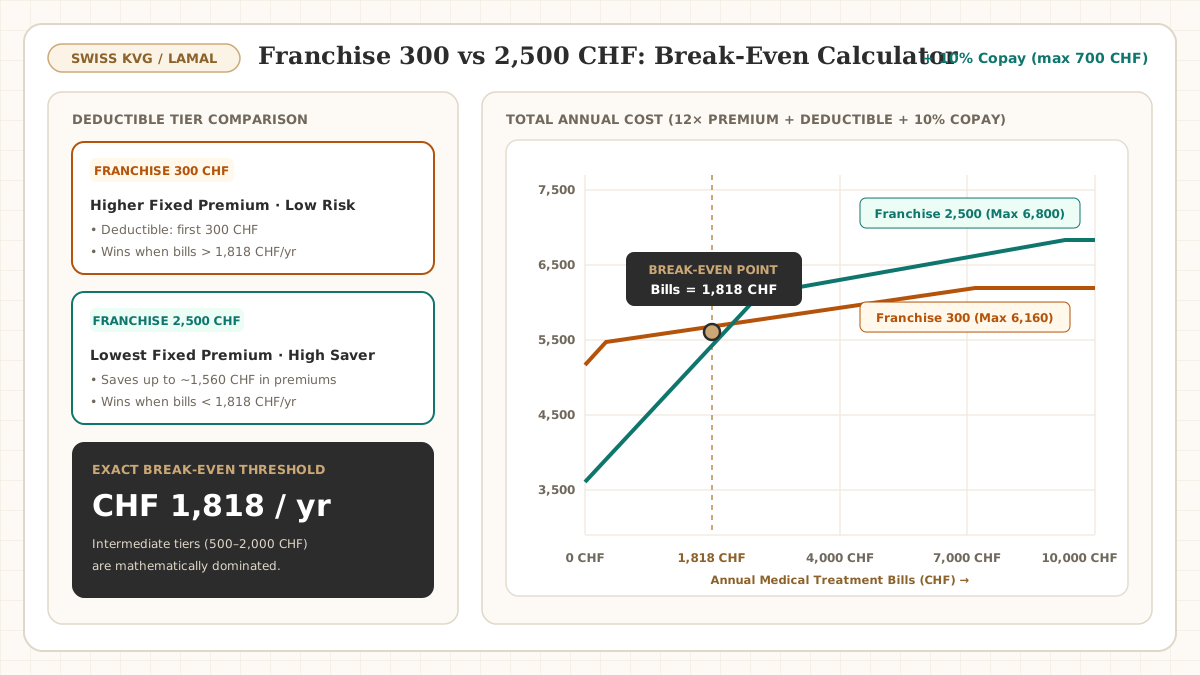
Swiss Health Insurance (KVG) – Choosing Between the 300 & 2,500 CHF Franchise
Interactive Swiss mandatory health insurance (KVG / LAMal) deductible comparator. Simulate annual medical expenses, fixed monthly premiums, and the 10% statutory copay (Selbstbehalt capped at 700 CHF/year) to find your exact break-even point.
Live Verdict Interactive Swiss KVG / LAMal health insurance calculator comparing the 300 CHF and 2,500 CHF franchise tiers, fixed annual premiums, 10% statutory copay (Selbstbehalt capped at 700 CHF), and exact mathematical break-even thresholds.
KVG Deductible Tiers
10% Copay Capped at 700 CHF
Franchise & Monthly Premium Setup
Enter your insurer's monthly basic insurance (Grundversicherung) premiums for each deductible tier.
Option 1 · Low Deductible
Annual Fixed: 3,972 CHF
CHF/Mo
Option 2 · High Deductible
Annual Fixed: 2,652 CHF
CHF/Mo
Live Expense Simulator
Saves 1,020 CHF/yr
Simulated Annual Medical Bills & Outlay
Drag the slider or enter gross annual doctor, hospital, and prescription bills to compare total out-of-pocket + premium cost.
Cost Progression Graph
Break-Even: 1,767 CHF
Total Annual Cost vs. Medical Bills Incurred
Total annual outlay = 12 × monthly premium + paid franchise deductible + 10% statutory copay (up to 700 CHF).
Decision Metrics
Statutory KVG / LAMal Analysis
Break-Even & Risk Thresholds
Key financial benchmarks explaining why intermediate deductibles (500–2,000 CHF) are almost always outperformed by the 300 or 2,500 CHF extremes.
Optimal Choice Now
Franchise 2,500
At 1,200 CHF medical bills
Net Annual Savings
1,020 CHF
Compared to runner-up model
Break-Even Medical Bills
1,767 CHF
Exact crossover threshold
Healthy Year Savings (0 CHF)
1,320 CHF
Guaranteed fixed premium reduction
Max Worst-Case Extra Risk
+880 CHF
At ≥ 9,500 CHF severe hospital bills
Liquidity Reserve Needed
3,200 CHF
High franchise + 700 CHF max copay
Comprehensive KVG Cost & Risk Comparison
| Financial Parameter | Option 1 (Franchise 300) | Option 2 (Franchise 2,500) |
|---|---|---|
| Monthly Premium | 331 CHF / Mo | 221 CHF / Mo |
| Fixed Annual Premium (12 Months) | 3,972 CHF | 2,652 CHF |
| Annual Deductible (Franchise) | 300 CHF | 2,500 CHF |
| Max 10% Statutory Copay (Selbstbehalt) | 700 CHF | 700 CHF |
| Minimum Annual Cost (0 CHF Doctor Visits) | 3,972 CHF | 2,652 CHF |
| Maximum Annual Cost (Severe Illness Cap) | 4,972 CHF | 5,852 CHF |
| Max Additional Risk vs. Option 1 | Baseline (0 CHF) | +880 CHF |
| Ideal Insured Profile | Ongoing prescriptions, chronic therapy, planned surgery, or expected annual bills above break-even. | Healthy adults with rare doctor visits and a 3,200 CHF emergency savings buffer. |